Google AI

Weekend Times


The Times

Business News

what Australians did with their super when COVID struck

  • Written by: Nathan Wang-Ly, PhD Student, School of Psychology, UNSW Sydney
what Australians did with their super when COVID struck

What happens when people withdraw their retirement savings early?

We’ve just found out.

During the first year of COVID Australians who faced a 20% decline in their working hours (or turnover for sole traders) or were made unemployed or were on benefits were permitted to take out up to A$10,000[1] of their super between April and June 2020, and a further $10,000 between July and December.

Five million took up the offer. They withdrew $36 billion[2].

Most of those surveyed by the Institute of Family Studies said they used the money to cover immediate expenses[3]. But definitions of “immediate” can vary.

Dan Peled/AAP Real time transaction card data appeared to show early withdrawers boosted their spending by an average of $3,000[4] in the fortnight after they got the money. One interpretation[5] said they spent the money on “beer, wine, pokies, and takeaway food, rather than mortgages, bills, car debts, and clothes”. In order to get a more complete picture, we obtained access to millions of anonymised transaction records of customers of Australia’s largest bank, the Commonwealth Bank[6]. The data included 1.54 million deposits likely to have been money withdrawn through the scheme including 1.04 million we are fairly confident did. Who dipped into super? The data provided by the bank allows us to compare circumstances of withdrawers and non-withdrawers including their age, time with the bank, and banking behaviour before COVID. We find withdrawers tended to be younger and in poorer financial circumstances than non-withdrawers before the pandemic. Six in ten of the withdrawers were under the age of 35, a finding consistent with data reported by the Australian Taxation Office[7]. Withdrawers tended to earn less than non-withdrawers, even non-withdrawers of the same age. Only 17% of withdrawers for whom we could identify an income earned more than $60,000 compared with 26% of non-withdrawers. And withdrawers had lower median bank balances ($618 versus $986). Read more: What happened when we gave unemployed Australians early access to their super? We've just found out[8] For those with credit cards and home loans, withdrawers were about twice as likely to be behind on repayments as non-withdrawers (9.7% versus 5.8% for credit cards, and 8.2% versus 3.4% for home loans). These characteristics suggest that, despite concerns of the scheme being exploited due to the application process not requiring any documentation[9], most of those using the scheme genuinely needed the money. Where did the money go? Compared to non-withdrawers, those who withdrew increased their spending (on both essential and discretionary items), paid back high-interest debts, boosted their savings, and became less likely to miss debt payments. Withdrawers spent an average of $331 more per month on debit cards in the three months after withdrawal, and $126 per month in the following three months. They spent an extra $117 per month on credit cards during the first three months, which shrank to an extra $13 per month in the following three months. The average withdrawer spent 7% more per month on groceries than the average age and income matched non-withdrawer, 12% more on utilities such as gas and electricity, 16% more on discretionary shopping, and 20% more on “entertainment,” a Commonwealth Bank category that includes gambling. Less debt, less falling behind In the three months that followed withdrawing, withdrawers also averaged $437 less credit card debt and $431 less personal loan debt than age and income matched non-withdrawers, differences that shrank to $301 and $351 in the following three months. They also became less likely to fall behind on credit card and personal loan payments, a difference that vanished after three months. Our interpretation is that the scheme achieved its intended purpose: it provided many Australians in need with a financial lifeline and helped buoy them during uncertain and turbulent times. Lessons learned At the same time, our findings[10] identify areas of concern. The fact that most withdrawals were for the permitted maximum of $10,000 highlights the need to carefully consider the withdrawal limit. While these sums might simply reflect the true amount of money individuals needed to sustain themselves, it might be that many withdrawers were unsure of how much to withdraw[11] – not knowing how long the pandemic would continue. Another consideration is how to best support withdrawers after they have taken out the money. More than half were under the age of 35, and might find themselves with a good deal less super than they would have in retirement. The government has already introduced tax concessions[12] for withdrawers who contribute funds back into their retirement savings accounts. Super funds might also be able to help, by sending targeted messages to those who have withdrawn. References^ A$10,000 (www.ato.gov.au)^ $36 billion (www.apra.gov.au)^ immediate expenses (aifs.gov.au)^ $3,000 (www.illion.com.au)^ One interpretation (www.stptax.com)^ Commonwealth Bank (www.sciencedirect.com)^ Australian Taxation Office (www.abc.net.au)^ What happened when we gave unemployed Australians early access to their super? We've just found out (theconversation.com)^ not requiring any documentation (www.abc.net.au)^ findings (www.sciencedirect.com)^ withdraw (cepar.edu.au)^ tax concessions (www.ato.gov.au)Authors: Nathan Wang-Ly, PhD Student, School of Psychology, UNSW Sydney

Read more https://theconversation.com/not-all-beer-and-pokies-what-australians-did-with-their-super-when-covid-struck-190911

The Weekend Times Magazine

Sydney Residents: Options for a Weekend Away Short Break

Living in Sydney offers an enviable lifestyle, but even the most iconic city in Australia can feel hectic at times. Whether it’s the daily commute, a fast-paced work schedule, or...

Who Can Install A Private Power Pole?

Private power poles provide property owners with the freedom to choose where electricity will enter the building. It also offers protection from hazards associated with being directly connected to the...
Catering Boxes: Practical Packaging That Supports Food Quality and Presentation

Reliable Catering boxes are essential for food businesses that need to transport, store, and present meals safely and professionally. From cafés and bakeries to large-scale caterers and event organisers, catering boxes...
Why Timely Air Conditioning Repair Is Important for Comfort, Efficiency, and System Longevity

A functioning air conditioning system is essential for maintaining a comfortable home, especially during warm weather. When the unit begins to show signs of trouble—such as weak airflow, unusual noises...
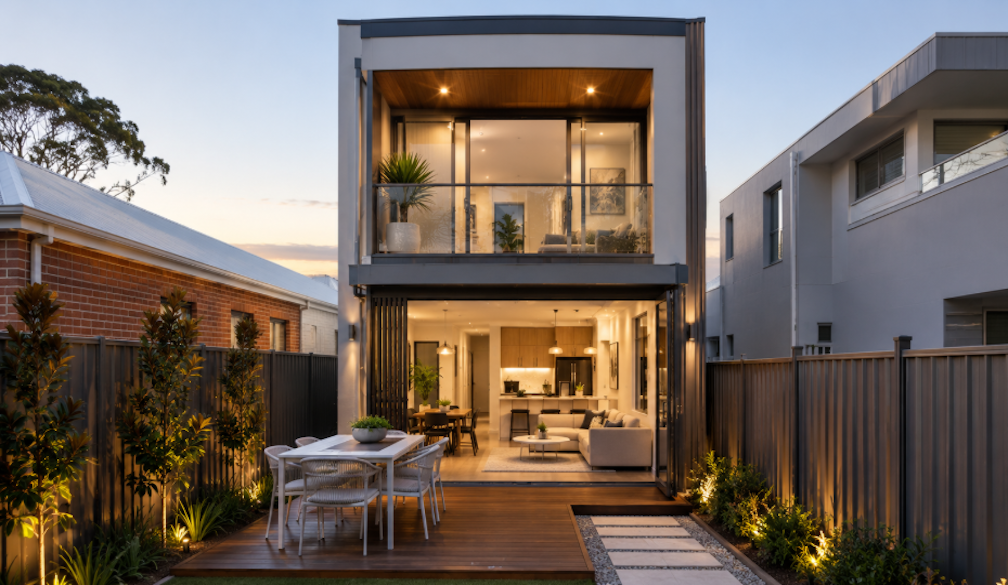
Building a Custom Home on a Narrow Lot in Mandurah: What the Block Size Is Not Telling You

Property listings in Mandurah's established suburbs increasingly include lots that look modest on paper. Widths of 8, 10, or 12 metres. Street frontages that seem to leave little room for...
Why Is My Toilet Not Flushing?

No one factor is responsible for toilets not flushing normally. Additionally, the reason behind this plumbing issue can also differ. The location, whether it is in a residential property or...
Last Call for Tradies Before Christmas

The Christmas bells might not be ringing for Santa yet, but they are fast approaching, and the sooner you start getting organised, the better. Before you start present shopping or...

Diamonds & Why They Are The Popular Choice For Any Occasion Here In Australia

Diamonds have been an incredibly popular gem for many years now and they continue to be so even now in 2024. It seems like the perfect jewel to choose for...
Unit and construction market looks towards a new era of stability

The peak strata industry body in New South Wales representing the interests of all strata industry stakeholders says it is confident the era of construction and certifier cowboys will come...